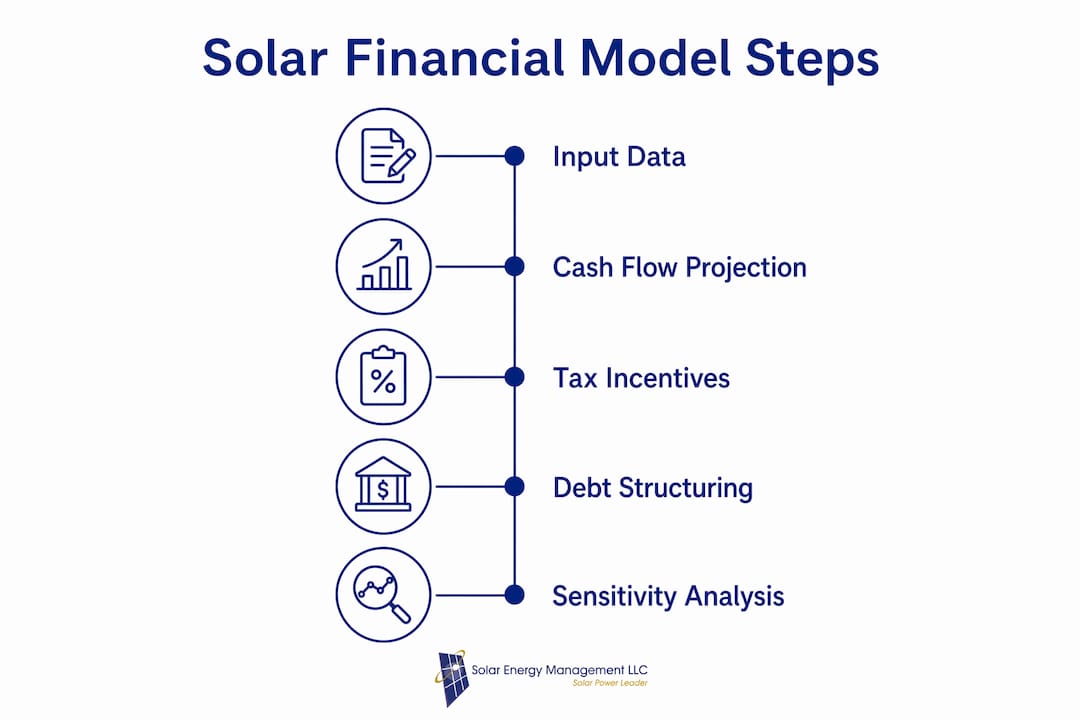
Solar energy financial modeling is the process of projecting a solar project’s cash flows, costs, capital structure, and returns to determine whether it is worth building and how it should be financed. For investors, developers, and lenders operating in the US market, a well-built model is not a formality. It is the decision-making instrument that determines whether a project gets financed, at what cost, and under what risk conditions.
The core elements of any solar financial model include:
- Capital expenditures (CAPEX): Equipment, EPC labor, interconnection, and development costs
- Operating expenditures (OPEX): Annual O&M, insurance, land lease, and asset management fees
- Revenue modeling: Power Purchase Agreement (PPA) pricing, capacity factors, and degradation schedules
- Financing structure: Senior debt, tax equity, and sponsor equity layers
- Tax incentives: Investment Tax Credit (ITC), Modified Accelerated Cost Recovery System (MACRS) depreciation
- Return metrics: Net Present Value (NPV), Internal Rate of Return (IRR), Debt Service Coverage Ratio (DSCR), and Levelized Cost of Energy (LCOE)
The stakeholders who rely on these models span the full capital stack. Lenders use them to size debt and test covenant compliance. Tax equity investors use them to confirm ITC monetization and after-tax IRR. Sponsors use them to optimize equity returns and stress-test assumptions before committing capital.
What goes into a solar energy financial model
Every solar financial model is built on a set of technical and financial inputs that feed into a projected cash flow statement. Get the inputs wrong, and the model will overstate returns and understate risk. The structure below reflects current best practice for US utility-scale and commercial projects in 2026.
Core inputs and outputs:
| Input Category | Typical Variable | Example Value (US Farm) |
|---|---|---|
| System capacity | DC/AC nameplate (MW) | — |
| Installed cost (CAPEX) | $/W installed | — |
| Capacity factor | % of theoretical max | 30% (single-axis tracker, Texas) |
| Annual generation | MWh/year | — |
| PPA tariff | $/MWh fixed | $30–$38/MWh for 20–25 years |
| OPEX | $/kW/year | $8–$10/kW/year |
| Panel degradation | %/year | 2.5–3% annually |
| OPEX escalator | Annual % increase | ~2.5–3% per year |
| ITC value | % of eligible basis | 30% base (plus bonuses) |
| Levered IRR target | Post-tax-equity | 8–11% |
Solar resource availability drives everything upstream of the revenue line. Analysts use P50 production estimates (50% probability of exceedance) for base-case modeling and P90 estimates for downside and lender cases. The gap between P50 and P90 typically reduces projected output by 5–8%, which can meaningfully shift DSCR and IRR.
Cash flow timing matters as much as the annual figures. Construction draws, interconnection payments, and ITC monetization all occur at different points in the project lifecycle. A model that treats CAPEX as a lump sum at year zero will misstate the construction loan balance and interest during construction (IDC), distorting the true cost basis.
OPEX escalators of approximately 2.5–3% annually must be modeled explicitly rather than held flat. Ignoring them leads to a systematic underestimation of long-term operational costs, which compresses actual cash flows relative to the model in later project years.
How project finance structures shape solar models
Solar project finance layers multiple capital sources against a contracted revenue stream. Understanding how each layer interacts with the model is the foundation of any serious solar finance strategy.
The capital stack for a typical US utility-scale solar project in 2026:
- Senior construction debt: 60–70% of total cost, priced at SOFR +175–250 basis points
- Tax equity: Remainder of the capital stack after senior debt, typically monetizing the ITC and MACRS depreciation
- Sponsor equity: Residual position, targeting levered IRR of 8–11% post-tax-equity
The Power Purchase Agreement sits at the center of the entire financing structure. Securing a PPA with a creditworthy offtaker is the single most important step in making a solar project financeable. Without a contracted revenue stream, lenders and tax equity investors will not commit capital. Fixed-price PPAs, typically escalating at 0–2% annually over a 10–25 year term, provide the revenue certainty that supports higher debt leverage and more favorable tax equity terms.
Tax equity financing works through a partnership flip structure. The tax equity investor, usually a large bank or corporation with significant US tax liability, invests cash in exchange for the ITC, MACRS depreciation benefits, and a small share of cash distributions. During the initial period of 5–8 years, the tax equity investor receives 99% of tax benefits and a small share of cash flow, targeting a 6–9% after-tax IRR. After hitting that return target, the allocation flips and the sponsor recaptures the majority of both tax benefits and cash flows.
Debt sizing aligns not just with total CAPEX but with PPA-backed cash flows. Lenders require a DSCR of 1.20–1.40x for contracted projects, and models must account for price basis risk between the project’s generation node and the PPA pricing hub. A covenant breach triggered by basis risk is one of the more common modeling failures in utility-scale solar.
You can explore how solar power financing options translate into project-level capital structures for both commercial and utility-scale contexts.
How solar business models affect financial projections
The business model a developer or investor chooses determines the shape of the cash flow profile, the timing of revenue recognition, and the risk allocation in the model. Each structure carries different implications for how you build and stress-test projections.
EPC (Engineering, Procurement, Construction): The EPC contractor receives payment in milestone-based draws during construction. Revenue is recognized as work progresses, and the model must track construction loan draws, interest during construction, and the transition to permanent financing at commercial operation date (COD). EPC margins are thin and front-loaded, with limited long-term revenue exposure.
Power Purchase Agreement model: The project owner sells electricity to an offtaker at a fixed price per MWh over a long contract term. PPA tariffs for US utility-scale solar commonly run $30–$38/MWh fixed for 20–25 years. This model produces stable, predictable cash flows that support project-level debt and tax equity. The financial model must capture annual generation degradation, OPEX escalators, and the merchant tail period after PPA expiration.
Solar-as-a-Service: The developer retains ownership of the system and charges the customer a monthly subscription or per-kWh fee. Revenue is recurring and recognized over the contract term. The model must account for customer churn risk, credit quality of the subscriber base, and the residual asset value at contract end. This structure is more common in commercial and industrial (C&I) and community solar contexts.
Community solar: Off-site subscribers receive bill credits in exchange for a share of a solar array’s output. The EPA notes that community solar supports low-to-moderate income subscribers and provides leasing revenue to property owners. Revenue modeling requires subscriber-level credit analysis, and the model must reflect the risk that subscriber attrition reduces contracted revenue below debt service requirements.
Understanding what a solar Power Purchase Agreement actually commits both parties to is essential before modeling PPA-based cash flows.
Key metrics and analytical techniques for solar investors
The metrics you prioritize depend on your position in the capital stack and your investment horizon. A lender cares about DSCR. A tax equity investor targets after-tax IRR. A long-term infrastructure fund focuses on NPV and LCOE. Each metric tells a different part of the same story.
NPV, IRR, and payback period are the three primary return metrics in solar financial modeling:
Net Present Value (NPV): The sum of all future project cash flows discounted to today’s value, minus initial investment. A positive NPV confirms the project creates value above the required return. For utility-scale projects, NPV analysis must incorporate the ITC monetization timing and the merchant tail period.
Internal Rate of Return (IRR): The discount rate at which NPV equals zero, expressed as an annualized return. Homeowners typically focus on payback periods of several years, while professional investors analyze IRR to assess capital efficiency and compare against alternative investments. Utility-scale projects target levered IRRs in the mid-to-high single digits post-tax-equity under stable PPAs.
Payback period: Simple payback divides net system cost by annual savings or revenue. Discounted payback, which accounts for the time value of money and panel degradation, gives a more accurate picture for long-duration assets.
Levelized Cost of Energy (LCOE) converts all project costs over its lifetime into a single $/MWh figure, enabling direct comparison against PPA prices and competing generation sources. The unsubsidized LCOE for US utility-scale solar ranged from $38–$78/MWh in 2025 according to Lazard’s analysis, dropping to $20–$45/MWh after accounting for the ITC or Production Tax Credit (PTC).
Sensitivity and scenario analysis are where models earn their value. Sensitivity analysis tests how a single variable, such as irradiance, energy price, or interest rate, affects NPV or IRR while holding everything else constant. Scenario analysis tests resilience against combinations of variables, such as a low-irradiance year coinciding with a counterparty credit event. Running a downside scenario where the PPA offtaker defaults or interconnection costs spike by $50M is not pessimism. It is the checkpoint that separates a financeable model from a wishful one.
Merchant risk, the exposure to wholesale power prices after PPA expiration, is one of the most undermodeled risks in long-duration solar assets. Lenders typically size debt to mature before the PPA expires, but equity investors must model the merchant tail explicitly to avoid overstating terminal value.
For a practical framework on applying these metrics to Florida projects, Solar Energy Management’s solar ROI calculator walks through the core inputs and outputs in a market-specific context.
US market factors every solar model must address in 2026
The US solar market in 2026 operates under a specific regulatory and financing environment that directly shapes model assumptions. Getting these details right separates a credible model from one that will not survive lender or investor due diligence.
The 30% Investment Tax Credit remains the most powerful lever in US solar project economics. The Inflation Reduction Act (IRA) extended and expanded the ITC, and bonus credits for domestic content and energy community siting can push the effective credit above 30%. Tax equity structures monetize this credit through the partnership flip mechanism described above, with tax equity providing approximately 35–50% of total project capital.
IRA transferability has broadened the buyer base for US solar tax credits. Developers can now sell ITCs directly to corporations at near-par value, simplifying financing and reducing dependence on traditional tax equity relationships. This has meaningfully lowered the cost of capital for smaller developers who previously lacked access to major bank tax equity programs.
MACRS depreciation allows solar assets to be depreciated over a five-year schedule under the Modified Accelerated Cost Recovery System, front-loading the tax benefit and improving early-year cash flows. Combined with the ITC, the tax benefit package in the first five years of a US solar project is substantial and must be modeled precisely to reflect actual cash timing.
The financing environment has tightened. Roughly 100 US solar companies filed for bankruptcy since 2023, driven by higher interest rates and reduced subsidies. Models that assume cheap capital or aggressive subsidy continuation without stress-testing those assumptions carry real execution risk.
Interconnection delays are now one of the primary development risks in US solar. MISO and PJM queue times can run 4–7 years, and late-stage transmission upgrade allocations can add tens of millions of dollars in costs not reflected in early-stage models. Any model built on a 2026 project announcement in MISO or PJM should assume a 2029–2031 commercial operation date.
Counterparty credit quality affects both the revenue line and the financing terms. A PPA with a rated investment-grade utility supports higher leverage and tighter debt pricing. A corporate PPA with a non-investment-grade offtaker requires a credit reserve or letter of credit, which increases costs and reduces equity returns.
For a detailed breakdown of how the ITC and accelerated depreciation apply to commercial projects, Solar Energy Management’s guide on solar energy tax credits covers the current federal framework with Florida-specific context.
Pro Tip: Always model OPEX with contractual escalators of 2.5–3% annually rather than flat costs. A flat OPEX assumption across a 25-year project life will systematically understate operational costs in years 15–25, compressing actual cash flows and overstating equity returns at the back end of the model.
For broader context on how cash flow timing and capital structure decisions interact across growth-stage businesses, the framework at Dynamic Growth Solutions offers a useful parallel perspective on disciplined financial planning.
If you are evaluating a solar project in Florida and need a financial model grounded in current market conditions, Solar Energy Management brings over 20 years of independent consulting experience to feasibility studies, system design, and project economics. Explore energy solutions tailored for commercial and residential clients across the state.
Key Takeaways
A credible solar energy financial model integrates PPA-backed cash flows, ITC monetization, MACRS depreciation, and OPEX escalators to produce defensible IRR and DSCR figures that survive lender and investor scrutiny.
| Point | Details |
|---|---|
| Capital stack structure | US utility-scale projects finance 60–70% senior debt, with the remainder consisting of tax equity and sponsor equity. |
| ITC and MACRS impact | The 30% ITC combined with five-year MACRS depreciation front-loads tax benefits and materially improves early cash flows. |
| PPA as financing backbone | Fixed-price PPAs at $30–$38/MWh for 20–25 years provide the contracted revenue that unlocks lender and tax equity capital. |
| OPEX escalators matter | Modeling O&M costs at 2.5–3% annual escalation prevents systematic underestimation of long-term operational expenses. |
| Levered IRR target | Post-tax-equity levered IRR for stable US utility-scale solar projects targets 8–11% under contracted PPA conditions. |
FAQ
What is the financial model of a solar project?
A solar project financial model projects all cash flows, costs, and financing terms over the project’s life, typically 25–30 years, to calculate NPV, IRR, DSCR, and LCOE. It integrates CAPEX, OPEX escalators, PPA revenue, ITC monetization, MACRS depreciation, and debt service to determine whether the project meets investor and lender return thresholds.
What is the business model of solar companies?
Solar companies operate under four primary models: EPC (construction contracts with milestone payments), PPA (long-term energy sales at fixed $/MWh), Solar-as-a-Service (recurring subscription revenue), and Community Solar (off-site subscriber arrangements). Each model produces a different cash flow profile and risk allocation that must be reflected in the financial model.
How do you make money with solar energy as a business?
Solar businesses generate returns through contracted PPA revenue, ITC and MACRS tax benefit monetization, and asset appreciation over the project life. Utility-scale developers target levered IRRs of 8–11% post-tax-equity, while tax equity investors target 6–9% after-tax IRR from the ITC and depreciation benefits.
Can I make money selling solar energy back to the grid?
Yes, through a PPA or net metering arrangement, though the economics depend heavily on the offtaker’s credit quality, the contracted price per MWh, and local grid interconnection conditions. US utility-scale PPA tariffs currently run $30–$38/MWh for solar-only projects on 20–25 year contracts, providing the revenue certainty that supports project-level debt financing.
What role does the ITC play in solar financial modeling?
The 30% Investment Tax Credit directly reduces the federal tax liability of the project owner and is typically monetized through a tax equity partnership flip structure. It provides a substantial share of the capital stack—typically the remainder after senior debt—and when combined with MACRS depreciation, it significantly improves early-year cash flows and reduces the effective cost of capital for the project.
Recommended
- Future Energy Solutions Florida: 2026 Guide – Commercial + Residential Solar Power Florida
- Solar Energy Tax Credits for Businesses: 2026 Guide – Commercial + Residential Solar Power Florida
- Solar Power Financing Options in Florida: A 2026 Guide – Commercial + Residential Solar Power Florida
- Solar Feasibility Study Explained: Your 2026 Guide – Commercial + Residential Solar Power Florida


